A Texas Car Insurance
Buying Guide
What policies you need, how much you should pay, and more, all brought to you from the perspective of a law firm who deals with insurance companies every single day. If you want to know that your next policy covers you adequately, and that you aren't paying too much, this guide can help.
You just got that dreaded letter in the mail: it’s time to renew your auto insurance. Your car is getting older, you have no accidents or tickets in your driving history, and yet, despite qualifying for numerous discounts, your rate only ever seems to go up.
Sure enough, it’s happened again. You might be wondering if it’s time to take your business elsewhere.
If this sounds like an all-too-familiar situation, you aren’t alone. Texas drivers fork over billions of dollars per year for coverage, so it’s only natural to want to keep your costs as low as possible. If you’re looking to switch providers or make some significant changes to your policy, then this guide has a wealth of information to help you make informed decisions regarding your auto insurance protection.
Insurance Pricing
How Much Is Car Insurance in Texas?
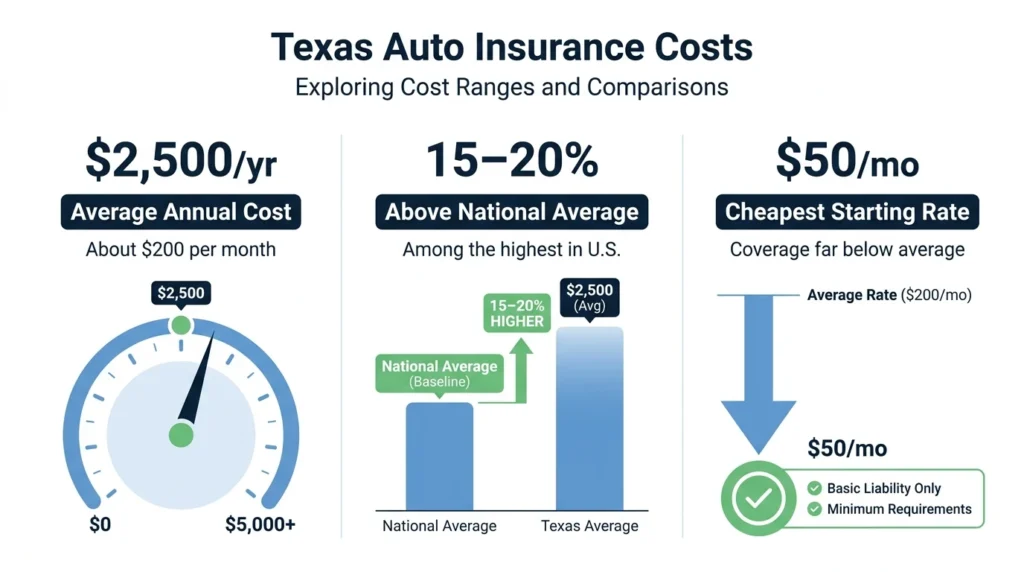
According to Insurify, a website for shopping around and comparing auto insurance quotes, Texas drivers pay around $2,500 per year for auto insurance, or just a little over $200 per month. This is one of the highest rates in the nation, exceeding national averages by around 10 percent.
However, your exact cost can vary from this number wildly. According to Insurance.com, Texas auto policies can start as low as around $50 per month. However, the type of protection you get for this value is dramatically lower than the average policy purchased in the state.
Factors That Influence Your Premiums
Your specific insurance rates will depend heavily on a multitude of factors. Here are just a few of them:
What kind of car are you insuring?
It’s much cheaper to insure a small, inexpensive commuter car like a Toyota Corolla or Hyundai Accent than it is to secure a larger luxury SUV like a Lexus or GMC. Generally, the more expensive the car, the more expensive it will be to insure.
Who is driving the vehicle?
Is this car going to be primarily driven by a teenager who just got their license, or a driver who has been behind the wheel for decades? Even so, how’s your driving record? Do you have any accident history, speeding tickets, or other moving violations on your record? Drivers who violate road laws are statistically more likely to be in an accident, so their coverage will likely cost more.
How old is the vehicle?
Two identical cars built 10 years apart will have dramatically different insurance rates. An older car is worth less, and therefore usually costs less to insure vs. a brand-new model.
Where does the driver live?
Those who live in urban areas or who frequently park on the street might pay higher rates than those who live in a rural or sparsely populated area. Accidents and theft rates are higher in densely populated cities, which can drive rates up.
What does your credit look like?
Texas is one of the states that lets insurers factor your credit history into your rate. Two drivers with identical cars and identical records can be quoted very different premiums if one has a strong credit profile and the other doesn’t.
How much do you drive?
A long daily commute means you’re traveling more miles every year than someone who works from home and only drives a few miles a few days a week. The more time you spend on the road, the higher the chance you file a claim, and insurers price that in.
Types of Insurance Policies Offered in Texas
Texas insurers offer several types of auto coverage, and understanding what each one does is the first step toward building a policy that actually protects you when you need it.
Liability coverage is the only type the state legally requires. It pays for the other party’s injuries and property damage when you are at fault, but it does not cover your own vehicle or your own medical bills.
Collision coverage pays to repair or replace your vehicle after a crash, regardless of who caused it. Comprehensive coverage handles damage from events outside your control, including hail, flooding, fire, falling objects, and theft. For a closer look at the differences, see our breakdown of collision, comprehensive, and liability coverage.
Texas weather alone is reason enough to take comprehensive coverage seriously. If you’re financing or leasing your vehicle, your lender will almost certainly require you to carry both.
Personal Injury Protection (PIP) and MedPay both cover medical expenses for you and your passengers after a crash, regardless of who was at fault. Texas law requires insurers to include PIP in every policy automatically. If you don’t want it, you’ll need to reject it in writing.
Finally, Uninsured/Underinsured Motorist (UM/UIM) coverage steps in when the at-fault driver either has no insurance or does not have enough insurance to cover your losses. Texas consistently ranks as one of the leading states for the number of uninsured drivers, which makes this coverage especially worth carrying. Our guide on PIP, MedPay, and UM/UIM coverage breaks down each option and what it costs to add.
When liability, collision, comprehensive, PIP, and UM/UIM are combined, that is what most people call full coverage car insurance.
Important Factors to Consider When Buying Insurance in Texas
Legal Minimums & Policy Limits
Texas law requires every driver to carry liability insurance. These numbers represent the minimum, not a recommended level of protection.
per person
per accident
per accident
Why Minimums Aren't Enough
A single serious accident can generate medical bills and property damage that far exceed those limits. When that happens, the at-fault driver can be held personally responsible for whatever the insurance doesn’t cover.
Carrying higher limits on your policy does increase your premiums, but it provides real protection for your savings, your home, and your income. For a full breakdown of what the law requires and why minimum coverage is often not enough, see our guide to Texas minimum car insurance requirements. The Texas Department of Insurance also maintains a consumer guide that explains your rights and what insurers are required to offer you.
Deductibles
Your deductible is the amount you pay out of pocket before your insurer covers the rest of a collision or comprehensive claim. A higher deductible means a lower monthly premium, but it also means a larger bill when you actually file a claim.
The right deductible depends entirely on your financial situation. If writing a $1,000 check tomorrow would create a genuine hardship, a lower deductible is worth the extra monthly cost. Our guide on how auto insurance deductibles work in Texas walks through the tradeoffs so you can make a decision that fits your budget.
Available Discounts
Most Texas insurers offer a range of discounts that can meaningfully reduce your premium. Common opportunities include:
-

Bundling.
Buying home and auto policies with the same carrier typically saves 10–26 percent
-
Defensive driving.
Completing an approved course can save you 5–10 percent on qualifying coverages for up to three years.
-
Telematics.
Usage-based programs track your driving habits and can reward safe drivers with savings of as much as 40 percent.
-
Good student.
Teen drivers on the policy with strong academic records often qualify for a reduced rate.
-
Low mileage.
Drivers who log significantly fewer miles than the state average can earn a lower premium.
Enrollment Requirements
When you apply for a policy, insurers evaluate several factors beyond your driving record. One of the most impactful is your credit score. Texas law permits insurers to use credit-based insurance scoring when calculating premiums, and the difference between good and poor credit can be significant. Drivers with weaker credit histories can pay considerably more for the same level of coverage compared to those with strong scores.
Understanding how this works gives you the opportunity to take steps that lower your rate over time. Our article on how credit scores affect car insurance rates in Texas covers the mechanics of credit scoring and what options are available to you.
Customer Satisfaction
Price matters, but it is not the only factor worth weighing. An insurer that is slow to pay claims, difficult to reach after a crash, or quick to deny coverage is not actually saving you money.
Before committing to a policy, check how each company handles claims. Look at independent consumer ratings and see whether any company has an unusual pattern of complaints on file with the Texas Department of Insurance. Our look at the worst insurance companies in America is a useful starting point for understanding what to watch out for.
Other Tips for Purchasing Insurance
Evaluate Your Coverage Needs Beforehand
Before you start collecting quotes, think clearly about what level of protection your situation actually requires. A paid-off vehicle with a low market value may not justify the added cost of full collision and comprehensive coverage. On the other hand, if you have meaningful assets to protect, relying solely on the state minimum in liability could put everything you’ve built at serious financial risk. Consider your vehicle’s value, your daily commute, who else will be listed on the policy, and what you could realistically absorb out of pocket after a crash.
Shop Around
Loyalty rarely pays off in the auto insurance market. The days of receiving a steep discount for years of repeated business are long gone—more often than not, insurers don’t factor in longevity at all anymore.
Rates for identical coverage can vary by hundreds of dollars a year between carriers, and insurers regularly reprice their books based on internal factors that have nothing to do with your behavior behind the wheel. Comparing quotes from multiple companies every one to two years is one of the simplest ways to make sure you’re not overpaying.
When you compare, make sure every quote is built on the same foundation: identical coverage types, matching limits, and the same deductible levels. A lower premium that comes with half the liability coverage is not a better deal.
Car Insurance Shopping FAQs
Does Texas auto insurance cover you if you drive into Mexico?
Usually not. Mexico does not recognize U.S. auto policies, so you usually need a separate Mexican liability policy before crossing the border.
Do any insurance companies force you to use their preferred repair shop?
They legally can’t. Under Texas insurance rules, you have the right to choose the repair shop and the parts used on your vehicle, although the insurer only has to pay a reasonable amount for repairs and parts of like kind and quality.
Insurers may recommend you go to their preferred shop, but you are not obligated to do so.
What happens if your car is totaled and you still owe money on the loan?
A standard auto policy usually pays the car’s market value, not the remaining loan balance. If you owe more than the vehicle is worth, gap insurance or loan/lease coverage may help cover the difference.
How long does your own insurance company have to respond to a claim in Texas?
In Texas, your insurer generally has 15 business days to acknowledge your claim and 15 business days after receiving the information it needs to accept or deny it, with a limited extension if it explains why more time is needed. Once the claim is approved, payment is generally due within five business days.
Can you get your deductible back after a Texas crash that was not your fault?
Sometimes. If you use your own collision coverage, your insurer may try to recover what it paid from the at-fault driver’s insurer, and if that happens, you might get some or all of your deductible reimbursed.
When an Accident Happens, We Can Help
Buying the right policy is about more than keeping monthly costs down. It is about making sure you are protected when something actually goes wrong. If you have been in a crash and are dealing with a claim, a coverage dispute, or an insurer that is not responding fairly, that is exactly what our firm is here for.
At Angel Reyes & Associates, we have more than 30 years of experience representing injured Texans and have recovered more than $1 billion for our clients. We offer free consultations, charge no fee unless we win, and are available 24/7. Reach out to us today if you have questions about a claim or need guidance on what your coverage should cover.
*Angel Reyes & Associates is not affiliated with any insurance company, including those both listed here and excluded from this list, and does not endorse or recommend any particular company over another. We always strongly recommend doing your own research and reaching out to companies for quotes tailored to your situation and your coverage needs.
All data presented in this piece is based on estimates/averages obtained at the time of writing, and is not intended to reflect or provide any realistic cost estimate for any particular company. All figures are speculative and purely for demonstrative, educational purposes only.
Past results do not guarantee future success.