Insurance Requirements for Commercial Trucks


Every article on this site is researched by our internal team, reviewed for legal accuracy against current Texas law, and held to State Bar of Texas advertising standards before publication. We do not publish content that overstates outcomes or makes promises about results.
Learn more about our
editorial standards .
Key Takeaways
- Truck insurance floors range from about $300,000 to $5,000,000 based on cargo and carrier type.
- Your own underinsured motorist coverage may pay when the trucker's policy falls short.
- Self-insured retention and umbrella policies can push real coverage past the stated minimum.
You’re driving north on I-45 outside Houston when an 18-wheeler drifts into your lane and slams your car into the guardrail. In the emergency room, someone mentions that the trucking company only had to carry a set minimum in insurance, and that number suddenly feels like a ceiling on what you can financially recover.
That figure is a floor, not a promise of everything that might actually be available to you.
How Much Insurance Must a Truck Carry?
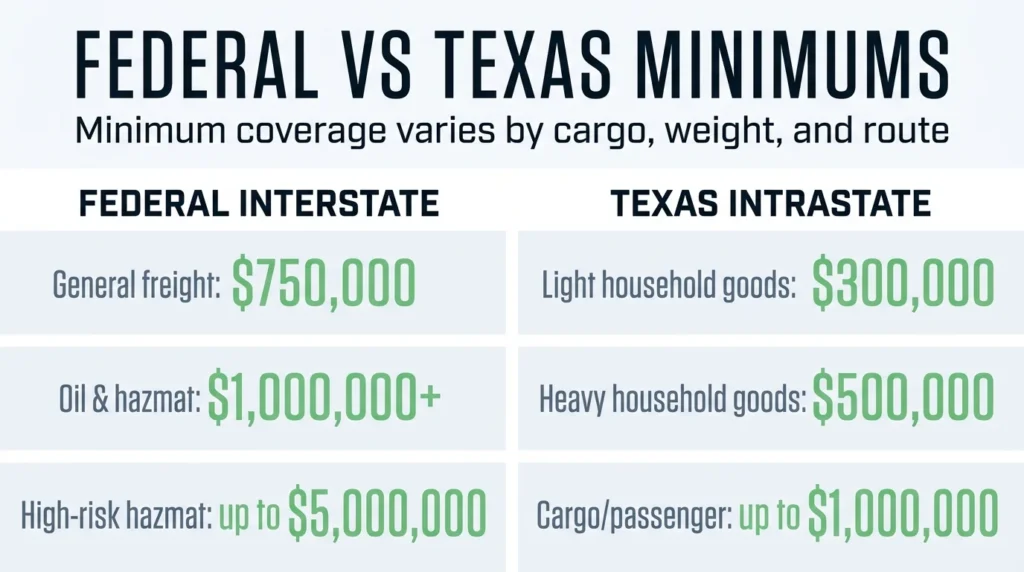
Trucking insurance is not one number. Coverage floors range from roughly $300,000 to $5,000,000, depending on cargo type, vehicle weight, and whether the carrier drives across state lines or stays inside Texas. Treat every figure below as a range, never as a guarantee of what your specific truck accident claim can recover.
Federal Minimum Coverage
Under 49 CFR § 387.9, general freight carriers must hold at least $750,000 in liability coverage. Oil and hazardous-materials haulers face a higher tier near $1,000,000 or more, and the highest-risk hazmat cargo can require coverage up to $5,000,000.
These tiers come from 49 U.S.C. § 31139, a law that has sat unchanged for decades. FMCSA’s own insurance filing requirements page confirms the amounts have stayed flat, which is part of why the federal floor can fall short of a serious injury’s real cost.
Texas Intrastate Minimums
43 Tex. Admin. Code § 218.16 sets lower ranges for carriers that never leave Texas. Lighter household-goods movers need roughly $300,000, heavier household-goods carriers need up to $500,000, and a combined-single-limit baseline near $500,000 commonly rises toward $1,000,000 for cargo and passenger operations.
Intrastate carriers must also keep an active state filing to operate legally. Confirming that filing is one of the first things an attorney checks when verifying a carrier’s standing.
Why the Minimum May Not Be Enough
A floor set decades ago that was never raised can fall well short of the real cost of a serious truck crash injury. Past case results show how quickly medical bills and lost wages can outpace a published minimum in a catastrophic or fatal case.
Your own auto policy may help fill that gap. Under Texas Insurance Code § 1952.101, insurers must offer underinsured motorist coverage on personal auto policies, and this coverage can respond when the at-fault trucking company’s policy is not enough.
Under Texas Transportation Code § 601.072, the state’s baseline auto liability minimums remain $30,000 per person, $60,000 per accident, and $25,000 for property damage, the same floor that has applied for years.
That baseline sets the starting point for the underinsured motorist floor tied to Section 1952.101, which factors in if you assume your own coverage automatically outpaces a serious truck crash. The Texas Department of Insurance explains how this coverage works.
If the truck that hit you was owned by the company itself rather than an independent driver, the
coverage picture can shift again.
Pull out your own policy’s declarations page and check your underinsured motorist limits. It is worth doing before you assume the trucking company’s minimum is the only money on the table.
How Coverage Layers Stack Above the Floor
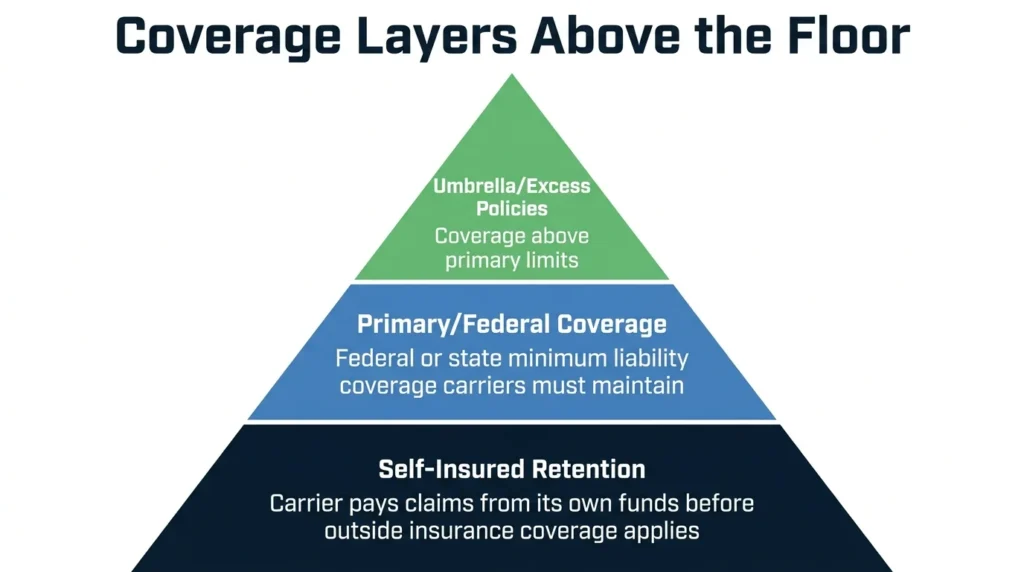
Larger carriers often absorb part of their own risk through self-insured retention . The carrier pays claims from its own funds up to a set amount, often hundreds of thousands of dollars, before an outside insurer’s coverage even applies.
Above that primary layer, many carriers also carry umbrella or excess policies. Once those layers are added in, the coverage truly available can run well past the minimum figure quoted online.
These layers are a reason to treat any stated minimum as a starting point for investigation. It is not the final word on what your claim is worth.
How to Find Out What Coverage Exists
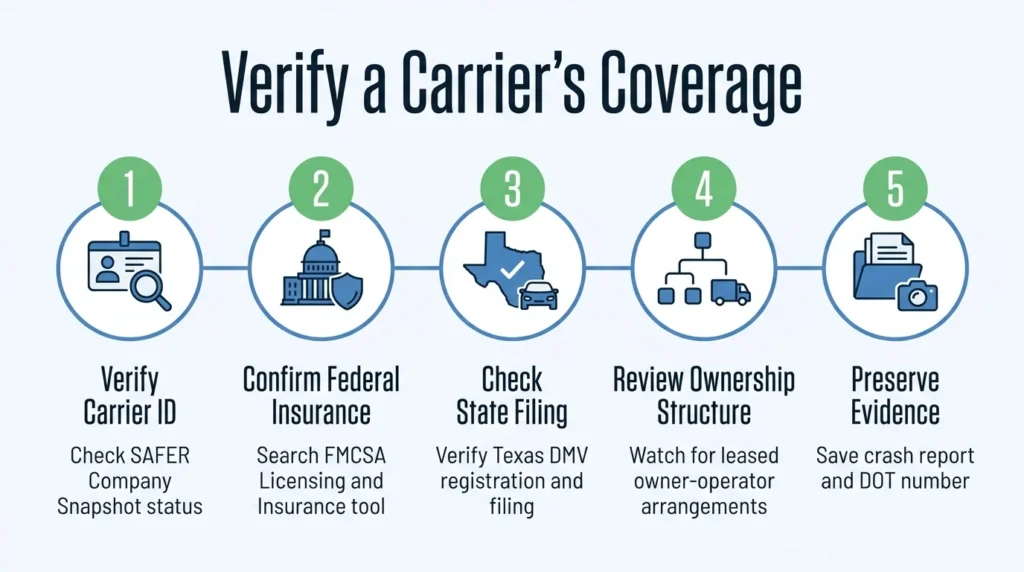
You do not have to accept a published minimum as the final answer. A few public records checks can show what a specific trucking company actually carries:
- Search the carrier’s name or DOT number in FMCSA’s SAFER Company Snapshot to confirm its identity, operating status, and whether insurance is currently on file.
- Use FMCSA’s Licensing and Insurance search to see the specific insurer, policy form, and filed coverage amount for an interstate carrier.
- For a Texas-only carrier, confirm active registration and insurance filing through the Texas DMV.
- Watch for complicated ownership structures and keep insurance rules for leased owner-operators in mind.
- Save the crash report and any carrier or DOT number information you have now. This paperwork gets harder to track down as time passes.
- Learn Texas’s claim-handling protections, including response and payment timelines, once a claim is filed against a commercial policy.
Why You Need Legal Help
An attorney can investigate every available policy layer, including self-insured retention and umbrella coverage, and can identify exclusions you would not find on your own.
Real outcomes in past truck cases show that recoverable amounts can exceed the stated minimum once every coverage layer is identified.
Speak With an Experienced Attorney
Angel Reyes & Associates has spent years helping injured Texans uncover what coverage a trucking company truly carries, not just the figure listed online. We work on contingency, so you pay no fee unless we win, and our attorneys have recovered more than $1 billion for clients.
Contact us today for a free case review.
Past results do not guarantee future outcomes.
Commercial Truck Insurance Claim FAQs
What is an MCS-90 endorsement, and how could it affect my claim?
An MCS-90 endorsement is a federal filing that forces a trucking company’s insurer to pay a judgment up to the required minimum coverage, even if a policy exclusion would otherwise block payment. The trucking company usually must reimburse the insurer afterward, so this rule protects injury victims rather than the carrier.
How long do I have to file a claim after a Texas truck accident?
Texas law generally gives injury victims two years from the date of the crash to file a personal injury lawsuit, under Civil Practice and Remedies Code Section 16.003. Missing that deadline can bar the claim entirely, so it helps to act well before it arrives.
If the truck that hit me was leased from an independent owner-operator, whose insurance covers the crash?
Federal leasing rules generally require the motor carrier to hold exclusive control and legal responsibility for a leased truck while it operates under that carrier’s authority. That usually means the carrier’s insurance, not the owner-operator’s personal policy, has to respond to the claim.
Does insurance still apply if the driver was not hauling a load or on duty at the time of the crash?
Coverage can depend on whether the driver was operating under the motor carrier’s authority at that moment. Separate non-trucking use or bobtail coverage often applies when a driver is off dispatch, and federal leasing rules require lease agreements to spell out who provides it.
About the Authors
Spencer Browne
Writer
Spencer Browne is a partner at Angel Reyes & Associates and a Board Certified personal injury trial lawyer with nearly 100 jury trials across Texas. He focuses on car, truck, and wrongful death cases, with notable verdicts including a landmark win in the Choctaw Casino bus crash case. A recognized speaker and legal educator, Spencer is a member of the American Board of Trial Advocates and has been honored as a Texas Super Lawyer and one of D Magazine’s Best Lawyers in Dallas. He brings deep trial experience and relentless advocacy to every client he represents.

Graham Griffin
Editor
Graham Griffin is the Web & Content Manager at Angel Reyes & Associates, where he oversees content strategy, AI-powered workflows, a...

Angel Reyes
Reviewer
Angel L. Reyes, III is the Founder and Managing Partner of Angel Reyes & Associates. A nationally recognized trial attorney and business...